Chase was losing real money on paper checks. We found a way to move those payments to Zelle, instantly.
Every month, Chase mails out around 4 million paper checks. The data made it clear that most of those recipients were already on Zelle.
Bill Pay and Zelle don't just store data differently, they run on entirely separate third-party back-end systems. The Zelle team uses one to track recipients, and Bill Pay uses a different one to manage payee details. Plugging them together directly was never going to happen.
So we worked around it. We focused on a specific group of billing companies: the ones that get paid by paper check today but also accept Zelle. If a company was already set up to receive Zelle, we could quietly route the customer there instead of cutting a check.
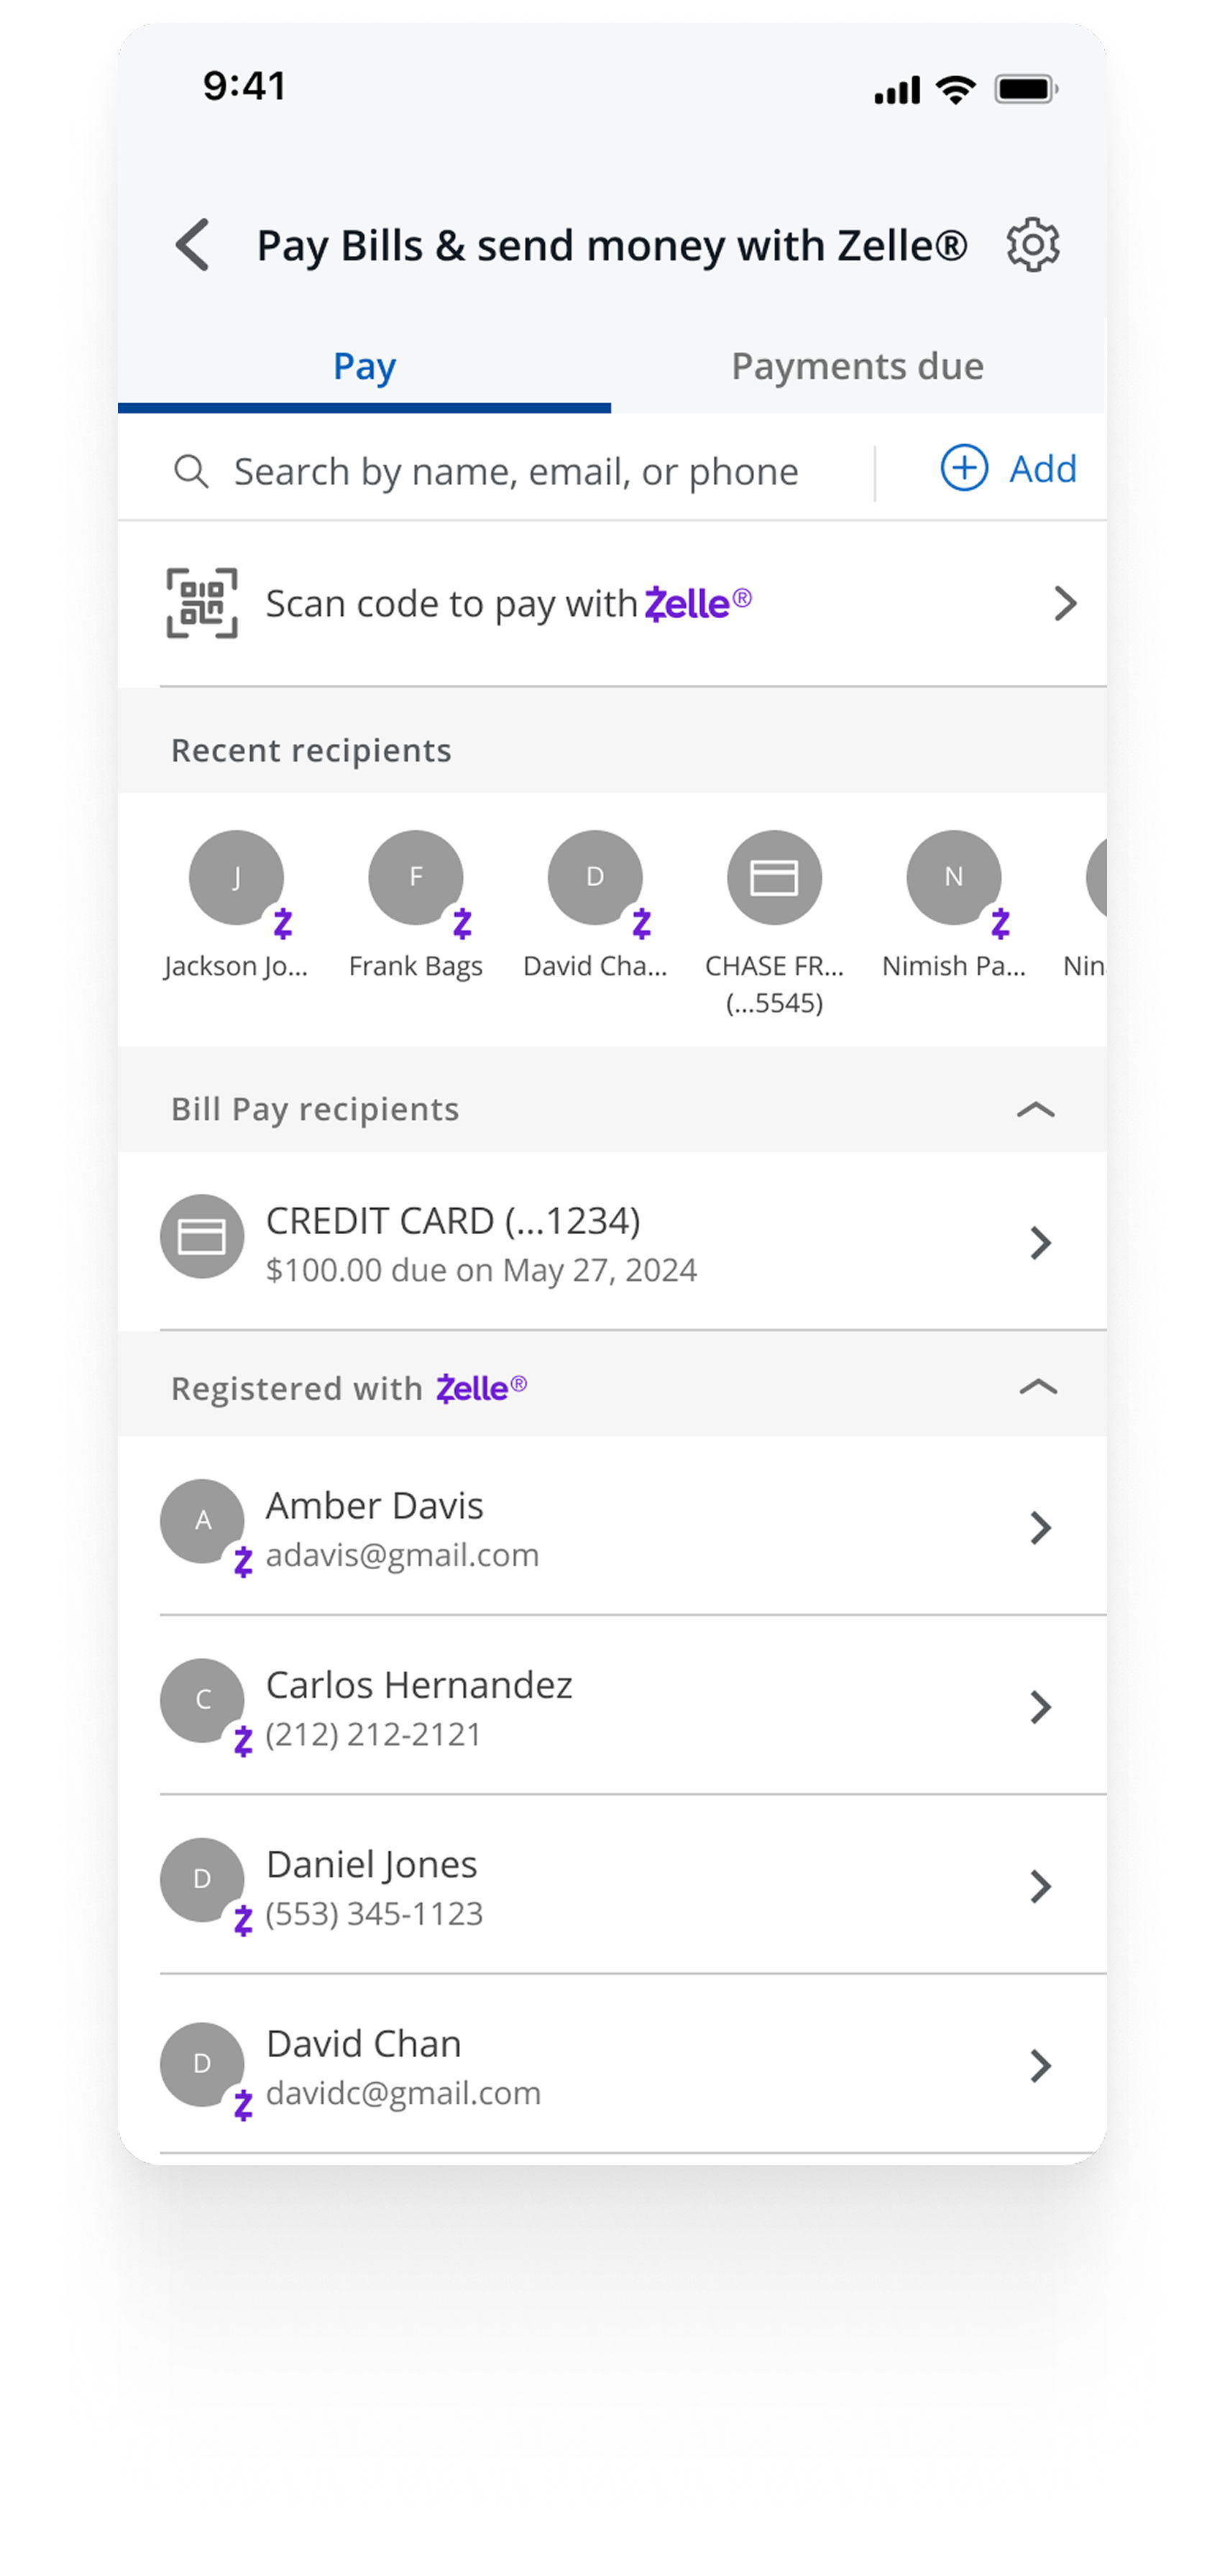
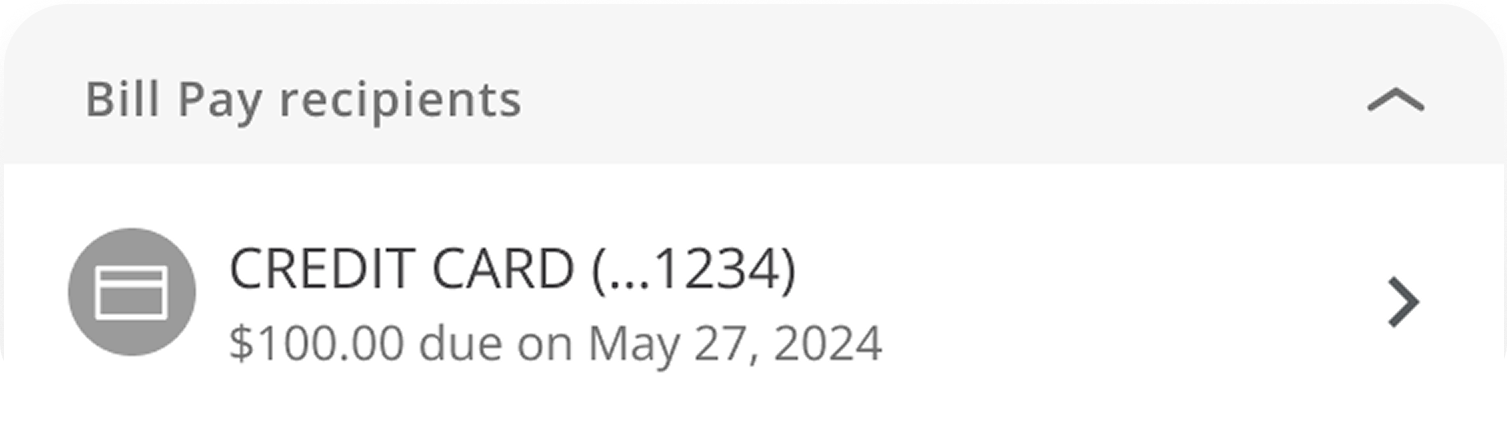
Bill Pay speaks in account numbers and payee addresses. A payee here is a biller and account number, like CREDIT CARD (…1234).
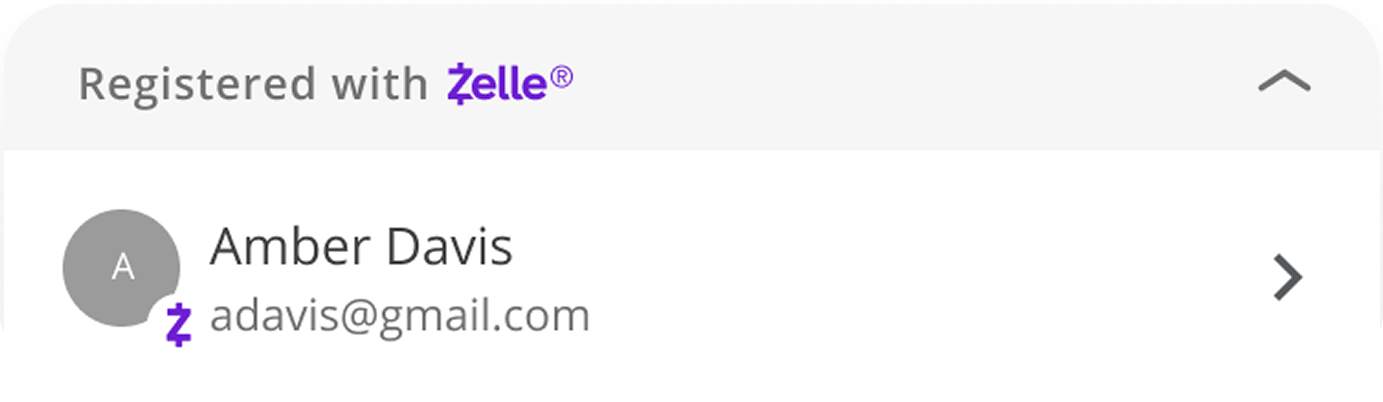
Zelle speaks in emails and phone numbers. A recipient here is a person, like adavis@gmail.com.
Before I touched a screen, we mapped the logic behind each concept: where Bill Pay and Zelle actually connect, what data we could pull, where the eligibility checks would live, and what the system needed to do at every step. Those maps became our anchor for syncs.
I made sure we weren't designing in a vacuum. From day one we looped in data, engineering from both sides, ADA, and legal. Data showed us what we could collect. Engineers told us what the systems could handle. ADA caught accessibility gaps early. Legal weighed in on whether moving customers between products mid-flow raised any flags, and reviewed our marketing copy to make sure nothing overpromised or could mislead a customer.
Bill Pay thinks in account numbers and addresses. Zelle thinks in emails and phone numbers. The hard part was bridging two systems that were never built to talk.
Capture value immediately with Phase 1, prove the system works with Phase 2, then remove the last bit of friction in Phase 3.
The goal was to move people from Bill Pay to Zelle, but I never wanted it to feel pushy. Every touchpoint sells the value of Zelle while keeping an easy path back. As a team, we agreed early this should be about persuasion, not pressure.
Instead of designing first and getting our copy shot down later, we brought legal in from the start to set guardrails on messaging. We landed on phrasing like "your money typically arrives in moments," language that felt persuasive and still passed legal.
Bill Pay and Zelle identify people differently, so we showed both sets of details and let customers confirm the match themselves. It felt more honest than asking them to trust a recommendation they couldn't see into.
Each phase builds on the one before it. Phase 1 plants the idea, Phase 2 proves the system works, and Phase 3 removes the last bit of friction, letting eligible customers skip the add-recipient step and land directly in a fully pre-populated Zelle flow. By handling the work progressively, we earned trust from our partners at every step.
Honestly, the hardest part was getting everyone bought into the logic maps. Aligning that many teams early isn't easy, especially on a tight timeline. But looking back, it was the most valuable thing we did. Having data, engineering, ADA, and legal all reviewing the same maps up front meant we caught the big problems before they turned into expensive rework.
The functional redirect works. The next step is making the transition feel like an upgrade.
With the timeline we had, a lot of the work was balancing what we could ship now against the long-term vision. If I had more time, I'd push harder on the UI-enhanced version, the one that feels like a real upgrade moment instead of just quietly moving someone between products.